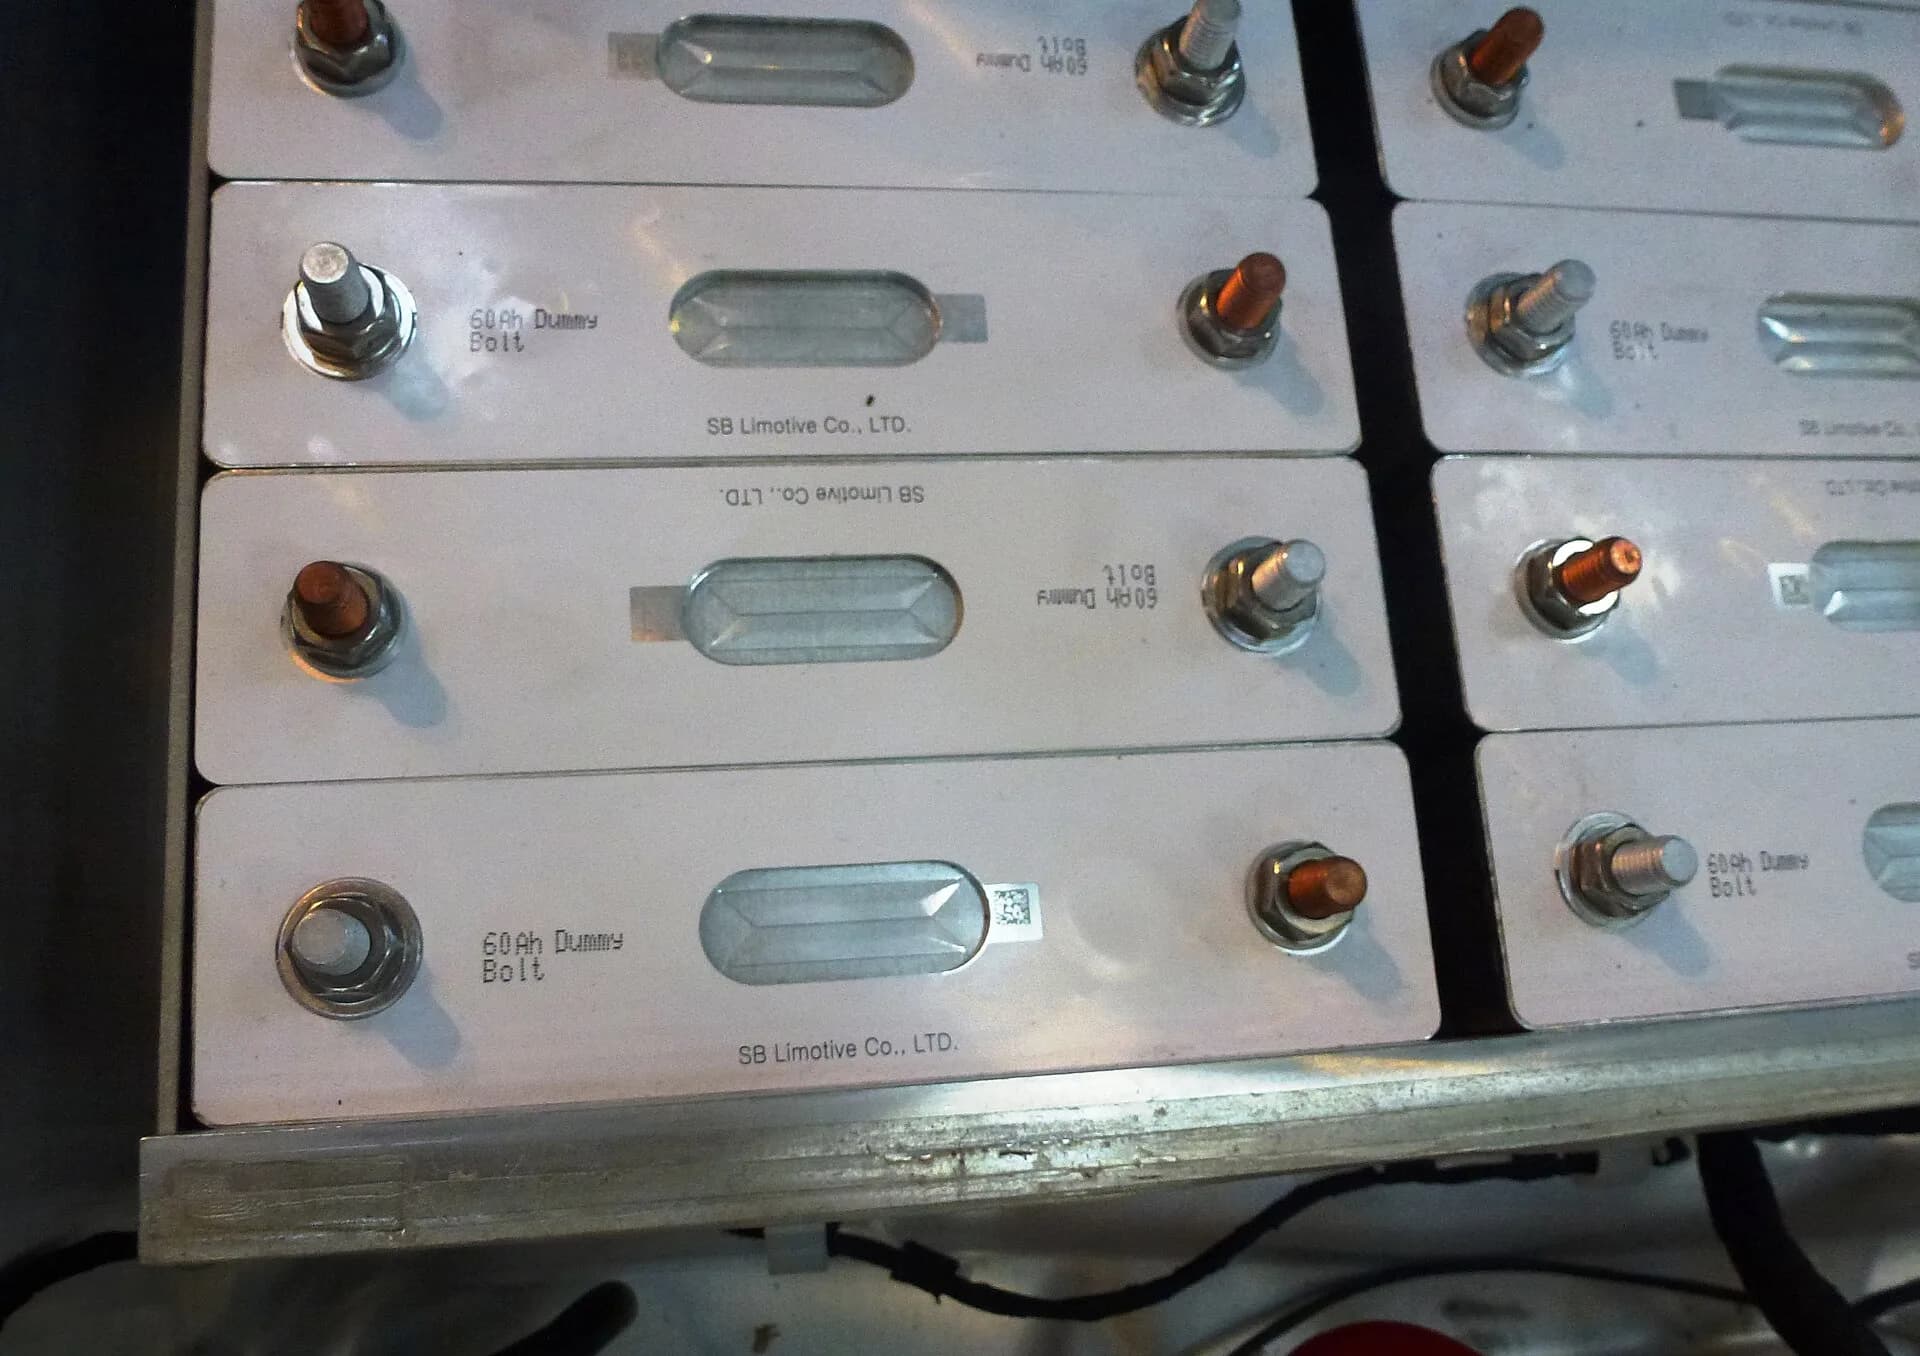
- At the 2026 World Manufacturing Convention in Hefei, Gotion raised the energy-density target for its sulfide-based Jinshi solid-state cells from 350 to 400 Wh/kg.
- The company also set a long-term cost goal of roughly one yuan per watt-hour (about US$150/kWh), which would be a first for solid-state manufacturing.
- Gotion says its cells survived puncture and high-temperature safety tests without smoke or fire, but has not published independent third-party test data to verify the claim.
A major cell manufacturer has put concrete numbers on both performance and price, a move that deserves a closer look even with a long timeline. What separates this announcement from earlier ones is commercial detail: price targets now sit beside energy density claims in the conversation.
That is what happened at the 2026 World Manufacturing Convention in Hefei, where Gotion High-Tech (China’s fifth-largest battery maker and Volkswagen’s largest single shareholder’s cell partner) laid out updated targets for its solid-state battery program. The sulfide-based Jinshi (金石, “Gold Rock”, also translated as “Gemstone”) cells are now aimed at more than 400 Wh/kg energy density in mass production, up from the 350 Wh/kg the company had previously specified.
The more striking announcement was financial. Gotion says its solid-state cells will eventually enter what it calls the “one-yuan era”: roughly one yuan per watt-hour, or about US$150/kWh. For a technology synonymous with luxury pricing, that would be a genuine milestone.
Doubling LFP, at double the price
To put the numbers in context: mainstream lithium iron phosphate (LFP) cells in China currently deliver roughly 160–200 Wh/kg at the cell level. Gotion’s 400 Wh/kg target would roughly double that, while the US$150/kWh cost target is about double today’s average LFP prices. In other words, the cells would offer about twice the energy density at twice the price: a premium but commercially coherent product, suitable for premium and performance EVs where range and weight matter more than price per kilowatt-hour.
Replacing the flammable liquid electrolyte of conventional lithium-ion cells with a solid material is the core of the solid-state promise: higher energy density and a fundamentally safer cell. Gotion backed up the safety claim with what it described as extreme testing scenarios, including puncture and high-temperature evaluations, in which the new cells produced neither smoke nor flames. That claim should be read with the standard caveat: it comes from the company’s own testing, with no published independent third-party verification. The chemistry’s theoretical advantages point in the same direction, but until outside labs replicate the results, “neither smoke nor flames” remains a company assertion.
From lab bench to pilot line
What separates this announcement from the usual solid-state vaporware is the industrialization trail behind it. Gotion commissioned a 0.2 GWh pilot production line for all-solid-state cells in 2025; cells from that line, at the 350 Wh/kg generation, were integrated into vehicles and tested on public roads. In March 2026, the company finalized the design of a 2 GWh solid-state battery production line, a tenfold capacity step toward the next development stage. Earlier, in early 2026, Gotion signed a cooperation agreement with BASF on high-performance solid-state battery materials, a signal that the company is working on the materials supply chain, historically one of solid-state’s trickiest bottlenecks.
The timeline Gotion laid out in 2024 still stands: small-scale solid-state production beginning in 2027, with mass production targeted around 2030. The 400 Wh/kg benchmark and the US$150/kWh cost figure are long-term targets attached to that 2030 horizon. Anyone reading the Hefei numbers as imminent should recalibrate: there is a four-year gap between announcement and the company’s own mass-production target.
A crowded race: where Gotion’s 2030 target sits
Gotion is not running alone. BYD’s executive vice president Stella Li said in September 2026 that the automaker will put solid-state cells in roughly 1,000 demonstration vehicles in 2027, a premium fleet for real-world data collection, with mass production not expected until around 2030. Taiwan’s ProLogium, meanwhile, signed a joint testing agreement with Mercedes-Benz in late September 2026 covering its Gen4 lithium-ceramic cells, building on a partnership that has run for nearly a decade.
Two more timelines put Gotion’s 2030 target in perspective. Samsung SDI is targeting mass production of sulfide-based all-solid-state batteries in the second half of 2027 at its Ulsan plant in South Korea, backed by a 25 trillion won investment program, the most aggressive timeline among major manufacturers, though the company’s CEO frames it as a target rather than a guarantee. Toyota, working with Idemitsu Kosan, aims to commercialize all-solid-state batteries in 2027–2028, but its own Toyota Times publication puts true mass production “for 2030 and beyond.”
The most sobering assessment comes from CATL’s chairman Zeng Yuqun, who said at the June 2026 Summer Davos forum in Dalian that the industry’s most advanced solid-state work had reached only level 4 on the nine-level technology readiness scale (laboratory proof of principle), and that all-solid-state batteries reaching million-vehicle deployment before 2030 was “very unlikely” (per Gasgoo’s report). Gotion’s 2030 mass-production target sits at the optimistic edge of that consensus: plausible for limited premium-vehicle volumes, but the million-vehicle scale CATL’s chairman doubts is a different milestone entirely.
The pattern across these announcements is instructive: sulfide-based cells from Gotion, BYD, and Samsung SDI on one side; ceramic and oxide approaches from ProLogium and others on the other. Each has different strengths (sulfides process more easily but are moisture-sensitive; oxides are more stable but harder to manufacture). No single chemistry has won, and the “mass production” claims that do exist still carry asterisks the size of small cars.
| Company | Near-term step | Mass-production target |
|---|---|---|
| Gotion (sulfide Jinshi) | 2 GWh line design finalized; small-scale production 2027 | ~2030; 400 Wh/kg, $150/kWh targets |
| BYD (sulfide) | ~1,000 demo vehicles in 2027 | ~2030 |
| Samsung SDI (sulfide) | S-Line pilot validating steps | H2 2027 at Ulsan |
| Toyota / Idemitsu | Commercialization 2027–2028 | 2030 and beyond (Toyota Times) |
| ProLogium (ceramic) | Joint testing with Mercedes-Benz (Gen4) | Not disclosed |
| CATL (assessment) | — | Million-vehicle scale before 2030 “very unlikely” (TRL4) |
What the $150/kWh target requires
The cost target deserves its own scrutiny, because it is the more radical half of Gotion’s announcement. Sulfide solid-state cells are expensive today for concrete reasons: lithium sulfide synthesis is costly, dry-room manufacturing at scale is unproven, and yields on sulfide cells have historically been brutal. Reaching US$150/kWh will require scale plus vertical integration in materials (Gotion has discussed manufacturing its own lithium sulfide to get there), plus yield improvements that no manufacturer has yet demonstrated at gigawatt-hour scale.
For context on how far there is to go: today’s average LFP pack prices in China sit around $75–85/kWh. Gotion is targeting roughly double that for a first-generation solid-state product, which, if achieved, would indeed be a breakthrough for the technology, but still leaves solid-state as a premium product for years.
Wh/kg vs $/kWh: solid-state’s commercial equation
Two numbers frame the stakes. Gotion’s $150/kWh target, if hit, would roughly double today’s Chinese LFP cell economics, but it would still sit about 85% above the $81/kWh average LFP pack price BloombergNEF measured in 2025, per our battery chemistry comparison. Solid-state’s commercial case was never going to be $/kWh; it’s Wh/kg. At 400 Wh/kg versus ~160–200 for LFP cells, Gotion’s target buys 2–2.5x the energy per kilogram of battery. That math matters most where weight is the binding constraint: long-range EVs and, increasingly, the data-center racks where QuantumScape is pitching solid-state in-rack storage. For grid storage, where weight doesn’t matter, LFP’s dollars-per-cycle advantage (see our LFP vs NMC grid-storage cost breakdown) remains the bar solid-state can’t yet clear.
Three tests for the Hefei targets
For the Gotion story specifically, three things will determine whether the Hefei announcements age into milestones or slide into the long archive of overpromised solid-state claims. First, the 2 GWh line: finalizing a design is not commissioning a plant, and yields on sulfide solid-state cells have historically been brutal. Second, the cost curve: reaching US$150/kWh will require scale plus vertical integration in materials, and Gotion has discussed manufacturing its own lithium sulfide to get there. Third, cycle life and real-world degradation data, which no one in the solid-state race has yet published in full, and independent safety verification, which Gotion has yet to provide.
Gotion’s position in the industry gives the announcement extra weight. Founded in 2006 in Hefei, the company is China’s fifth-largest battery maker with 20 manufacturing bases worldwide, and Volkswagen is its largest shareholder. According to China EV DataTracker figures cited in industry coverage, Gotion installed 4.61 GWh of batteries in August 2026 alone, trailing second-tier peers like EVE Energy and CALB, but large enough that its solid-state program isn’t a side project. When a manufacturer at this scale locks in a 2 GWh line design and publishes cost targets, suppliers, automakers, and competitors recalibrate. The sulfide electrolyte route Gotion has chosen is one of the industry’s main bets: sulfides can be processed at relatively low temperatures and conduct lithium ions well, but they’re notoriously sensitive to moisture, which makes dry-room manufacturing a decisive variable in who actually reaches mass production first.
Still, the trajectory is real. Solid-state batteries are moving from press-release chemistry to pilot-line engineering, and price targets now sit beside energy density claims in the conversation. That shift, more than any single number, is the signal that this technology is finally being treated as a product. The realistic read of the story: Gotion’s targets are the most commercially detailed in the industry, its industrialization trail is real, and its 2030 timeline sits at the optimistic edge of what even competitors think is possible.