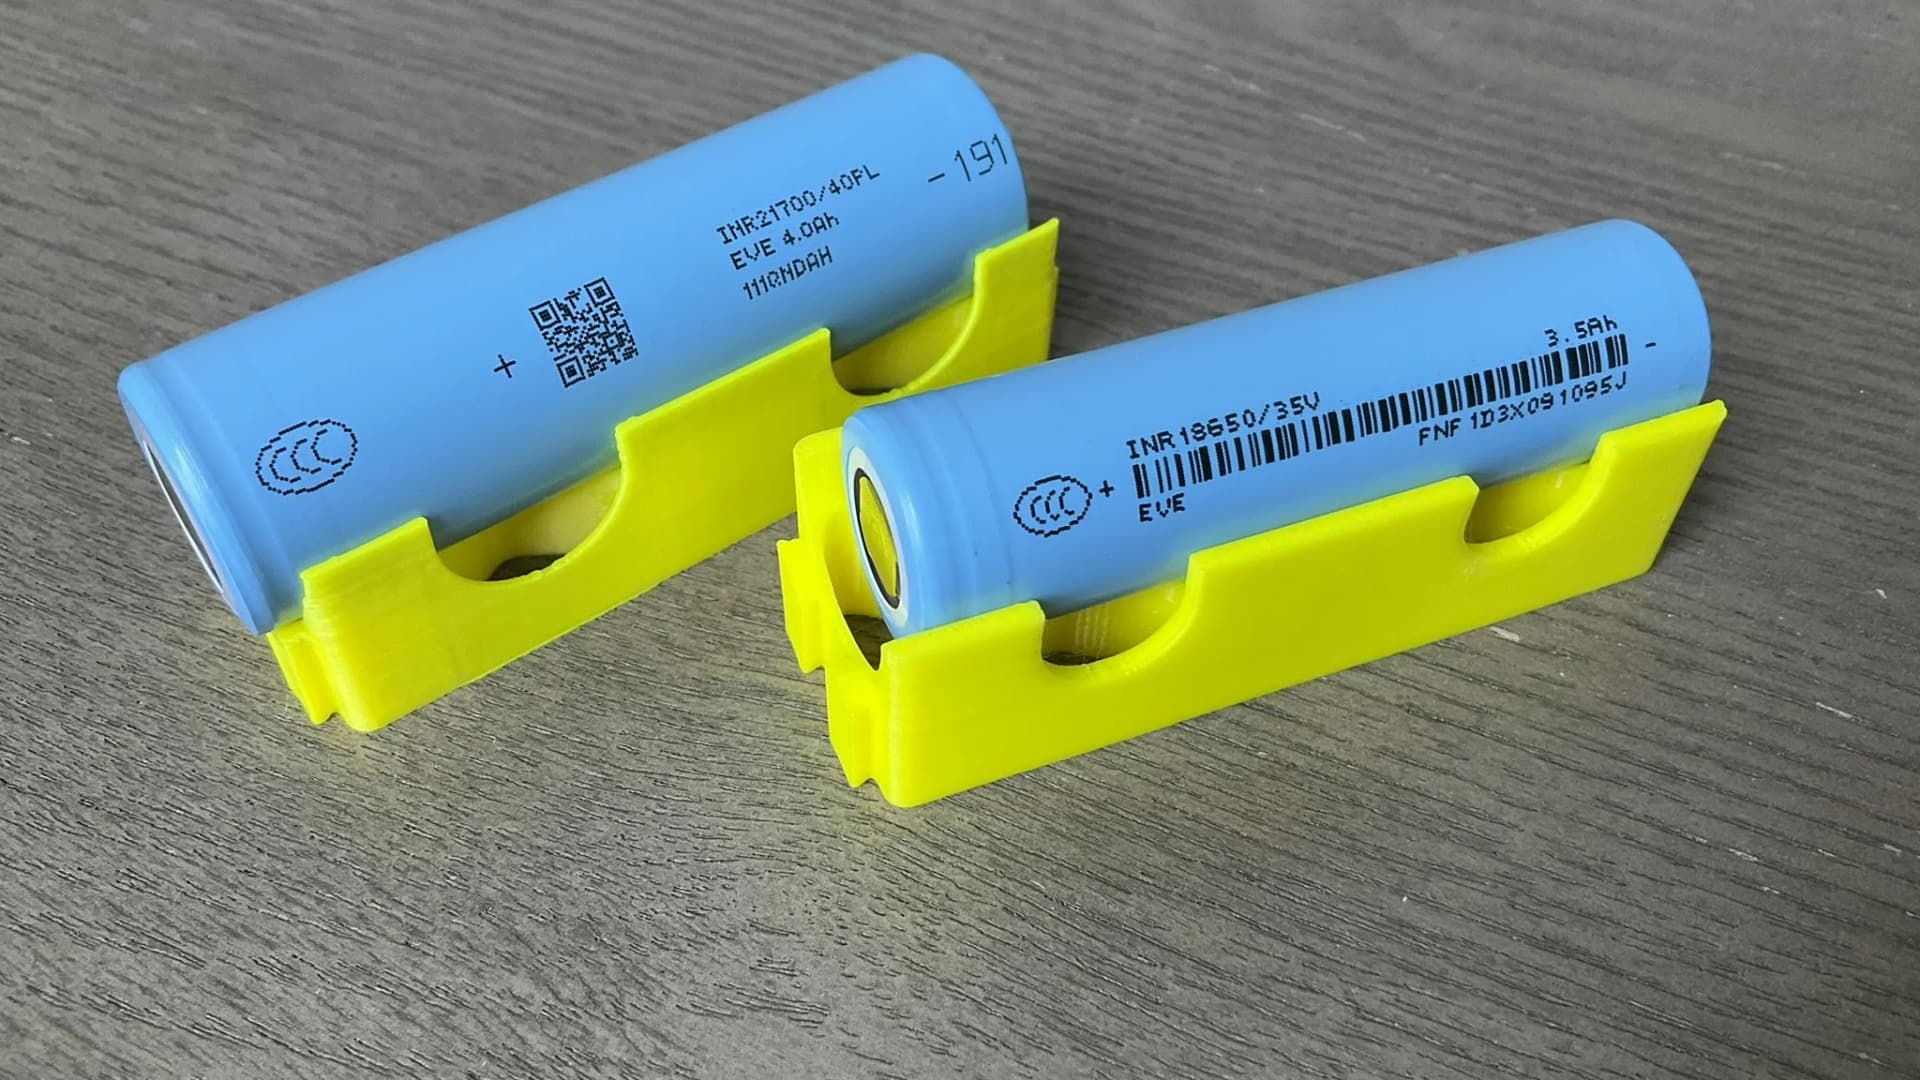
- Batteries aren’t one technology. The chemistry inside the cells (LFP, NMC, or the emerging sodium-ion) decides how much energy fits in a given weight, how many charge cycles it survives, and what it costs.
- LFP (lithium iron phosphate) is the workhorse: cheaper, longer-lived, and safer, which is why it dominates grid storage and affordable EVs. NMC trades some of that for higher energy density in long-range cars.
- Sodium-ion is the newcomer to watch: made from abundant salt instead of lithium, with early grid-scale deployments in China and a landmark 60 GWh order from CATL.
Battery chemistry: Average lithium-ion pack prices fell 20 percent in 2024 to a record low of $115 per kilowatt-hour, and that price collapse is what turned chemistry choice from a lab debate into a purchasing decision.
Why the chemistry inside a battery matters
When people say “lithium-ion battery,” they’re describing a family of technologies with a shared shuttle mechanism. Every lithium-ion cell shuttles lithium ions back and forth between two electrodes, but the materials those electrodes are made from change almost everything about the battery: how much energy it packs per kilogram, how many times you can charge it before it wears out, how hot it can get before it becomes dangerous, and how much it costs to make.
Getting this right matters because batteries have become the backbone of the energy transition. They power electric cars and store solar and wind power for the hours when the sun isn’t shining. And they’ve been getting dramatically cheaper: BloombergNEF’s annual survey found the average lithium-ion pack price fell 20 percent in 2024 to a record low of $115 per kilowatt-hour, driven by manufacturing overcapacity, falling metals prices, and the rise of cheaper chemistries. The chemistry split matters enormously for price: BNEF’s 2025 survey put the average LFP pack at just $81/kWh versus $128/kWh for NMC, a 58 percent premium for nickel-based chemistry. Stationary storage packs, overwhelmingly LFP, averaged only $70/kWh, according to Renew Economy’s coverage of the survey. “The price drop for battery cells this year was greater compared with that seen in battery metal prices, indicating that margins for battery manufacturers are being squeezed,” said Evelina Stoikou, head of BNEF’s battery technology team. For the full cost picture in stationary applications, see our LFP vs NMC grid-storage cost breakdown.
LFP: the workhorse
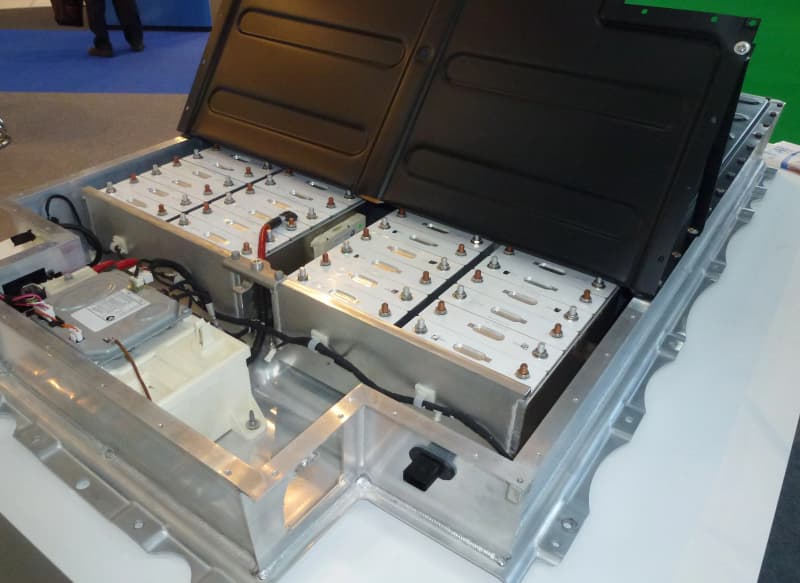
LFP stands for lithium iron phosphate (LiFePO₄): lithium paired with iron and phosphate instead of expensive metals. It is the chemistry quietly winning the battery race.
- Energy density: roughly 90–160 Wh/kg at the cell level, respectable, but lower than its rivals.
- Cycle life: 2,000 to 6,000+ full charge-discharge cycles, two to three times what nickel-based chemistries manage. A battery cycled daily for 15+ years is realistic.
- Safety: the standout trait. LFP cells resist thermal runaway (the self-heating chain reaction behind battery fires) up to around 270°C, far higher than nickel chemistries, and release little oxygen when they do fail.
- Cost and materials: iron and phosphate are abundant and cheap. No cobalt, no nickel, sidestepping the price volatility and supply-chain concerns around those metals.
- Charging: LFP cells can be charged to 100% routinely without the accelerated degradation nickel chemistries suffer, which simplifies daily use.
LFP’s one real weakness is energy density: you need a bigger, heavier pack for the same range. But where weight doesn’t matter much, it wins decisively. That is why LFP dominates grid-scale storage, including Tesla’s Megapack and CATL’s containerized systems, plus home batteries like the Tesla Powerwall, electric buses, and affordable EVs such as the Tesla Model 3 Standard Range. Per BloombergNEF, LFP’s share of the EV battery market hit roughly 40 percent globally in 2024 (60 percent in China), up from just 10 percent in 2020, and it accounts for the large majority of stationary storage deployments. For how storage systems actually earn their keep on the grid, see our battery energy storage explainer; for the residential trade-offs, our LFP vs NMC home-battery comparison and guide to home battery lifespan go deeper.
NMC: the long-range option
NMC (nickel manganese cobalt) is the chemistry that made the modern long-range EV possible.
- Energy density: roughly 150–250 Wh/kg, meaning significantly more driving range from a smaller, lighter pack.
- Cycle life: around 1,000–2,500 cycles, solid, but meaningfully shorter than LFP.
- Safety: thermal runaway can begin around 150–210°C, and the chemistry releases significant oxygen during failure, which is why NMC packs need more sophisticated cooling and battery-management systems.
- Cost: higher, driven by nickel and cobalt. Both metals have volatile prices and concentrated supply chains.
- Cold weather: a genuine advantage. NMC retains more usable capacity in freezing temperatures than LFP.
NMC remains the choice where every kilogram counts: premium, long-range electric cars, and applications with tight space constraints. But its share has been sliding as LFP’s energy density has improved enough for mid-range EVs and as automakers have grown wary of cobalt costs. The industry’s direction of travel is clear: use NMC where range-per-kilogram is the priority, LFP everywhere else.
Sodium-ion: the newcomer
Here’s the most interesting development in batteries: cells that contain no lithium at all. Sodium-ion batteries swap lithium for sodium, which is roughly 1,000 times more abundant in Earth’s crust than lithium, and they are moving from laboratory curiosity to commercial product faster than most people expected.
The leader is CATL, the world’s largest battery maker. Its Naxtra sodium-ion battery for vehicles reaches 175 Wh/kg, within striking distance of LFP, with mass production targeted for the end of 2026, according to Energy Storage News. For grid storage, CATL has unveiled a separate large-format sodium-ion cell rated at about 160 Wh/kg, more than 15,000 cycles at 80 percent capacity retention, 97 percent round-trip efficiency, and an operating range of −40°C to 70°C, while showing no thermal runaway in nail-penetration, crush, or overcharge tests.
A note on cycle-life numbers: cycle-life figures from different manufacturers are not directly comparable. Test conditions (depth of discharge, charge rate, temperature, and the capacity-retention threshold: 80% vs 70%) vary widely, and vendors typically publish best-case results. Treat CATL’s 15,000-cycle claim and the 2,000–6,000 range for LFP as indicative figures from different test regimes.
Sodium-ion’s advantages run deeper than chemistry alone:
- Materials: cobalt-free, nickel-free, and lithium-free, using aluminum foil instead of copper, all of which points to lower long-term costs as supply chains mature.
- Cold weather: sodium-ion outperforms even NMC in the cold. CATL’s first-generation cells retain more than 90 percent of capacity at −20°C.
- Safety: the chemistry is intrinsically less prone to combustion than lithium-ion designs.
The commercial signal is getting hard to ignore. China connected its first large-scale sodium-ion storage station in 2024, and in 2026 CATL signed what CATL describes as the largest sodium-ion order in history: 60 GWh of sodium-ion batteries for grid-scale storage with Beijing HyperStrong, roughly double what CATL shipped in storage cells across all chemistries the previous year. Manufacturing is scaling too: CBAK Energy’s 12 GWh sodium-ion plant in Nanjing shows the capacity race is already underway.
What sodium-ion costs today
CATL has claimed its Naxtra sodium-ion cells could reach $19/kWh at the cell level at volume, a figure that would undercut even LFP. But independent analysis urges caution: sodium-ion is currently estimated to cost roughly the same as, or somewhat more than, LFP cells, which remain cheaper thanks to massive manufacturing scale. The $19 figure is a forward-looking target at massive scale, still years from today’s price. For now, sodium-ion’s cost advantage is potential, not realized.
The recycling problem nobody prices in
Battery economics don’t end at purchase, and here the chemistries diverge sharply. NMC recycling is profitable today: recovered nickel and cobalt command high commodity prices, with NMC recycling revenue estimated at $1,100–2,200 per ton against processing costs of $1,200–1,600 per ton, according to Mordor Intelligence. LFP recycling loses money: processing costs $900–1,200 per ton while recovered lithium, iron, and phosphate are worth only $300–600. Without regulatory mandates or subsidies, recyclers have little incentive to process LFP, a growing problem as LFP’s market share climbs toward a majority of end-of-life batteries. On calendar aging, LFP also degrades more slowly when sitting idle, which favors it for backup-power and seasonal storage roles where batteries spend long periods at rest.
Which chemistry wins? It depends on the job
| Chemistry | Energy density | Cycle life* | Pack cost (BNEF 2025) | Strengths | Typical uses |
|---|---|---|---|---|---|
| LFP | ~90–160 Wh/kg | 2,000–6,000+ | ~$81/kWh | Low cost, long life, very safe, no cobalt | Grid storage, home batteries, affordable EVs, buses |
| NMC | ~150–250 Wh/kg | 1,000–2,500 | ~$128/kWh | Highest energy density, good cold performance | Long-range and premium EVs |
| Sodium-ion | ~160–175 Wh/kg | 2,000–15,000+ | ~$19/kWh cell (CATL’s at-scale target) | Abundant materials, excellent cold performance, very safe | Grid storage, budget EVs, cold climates (emerging) |
*Cycle-life figures use different test conditions across manufacturers and are not directly comparable; see note above.
There is no universal winner, but the decision rules are getting clearer. For grid storage, buy on dollars-per-cycle: LFP wins today at $81/kWh pack prices, and sodium-ion becomes the challenger to watch only if CATL’s $19/kWh cell target materializes at scale. For EVs, buy on dollars-per-kilometer of range: NMC justifies its $128/kWh premium only where pack weight directly limits the product, the long-range and premium segments. Everywhere else, LFP’s lower cost, longer life, and tolerance for 100% daily charging make it the rational default, which is exactly why its EV market share tripled since 2020. For cold climates, test before you commit: sodium-ion’s −20°C performance is its most proven edge over both lithium chemistries. Understanding these trade-offs (energy density versus lifespan versus cost versus safety versus recyclability) is the key to reading almost every battery announcement you’ll see in the next decade.
A container of grid storage doesn’t care about weight, so it wants the cheapest dollars-per-cycle, which today means LFP and tomorrow may mean sodium-ion. A sports sedan cares intensely about weight, so it pays the NMC premium. That single trade-off (density versus lifespan versus cost versus safety) is what organizes the next decade of battery news.
Frequently asked questions
Which battery chemistry is best for home storage?
LFP, for most households. Its long cycle life, tolerance for routine 100% charging, and strong thermal stability suit the daily charge-discharge rhythm of a home battery better than NMC’s density advantage, which matters little when the battery sits in a garage. See our LFP vs NMC home-battery comparison for the full breakdown.
Is sodium-ion available in electric cars yet?
Not at scale. CATL targets mass production of its 175 Wh/kg Naxtra sodium-ion vehicle battery for the end of 2026, while early grid deployments are already running in China. Budget EVs and cold-climate models are the most likely first adopters, since sodium-ion’s cost and low-temperature performance matter most there.
Are NMC batteries being phased out?
No; they’re being specialized. NMC’s share is sliding as LFP’s energy density improves, but its energy-density advantage keeps it dominant in long-range and premium EVs, where every kilogram counts. Expect NMC to hold that segment for years.
Why doesn’t LFP recycling pay for itself?
Recovered iron and phosphate are cheap commodities, so processing costs ($900–1,200/ton) exceed the value of recovered materials ($300–600/ton). Policy mandates, subsidies, or improved lithium-recovery processes will be needed as LFP volumes approach a majority of end-of-life batteries.