- India’s wind energy capacity is set to grow 8 GW in FY26-27 and scale to 13.2 GW a year by FY30-31, taking cumulative installations to about 107 GW, the industry body IWTMA announced at Windergy India 2026.
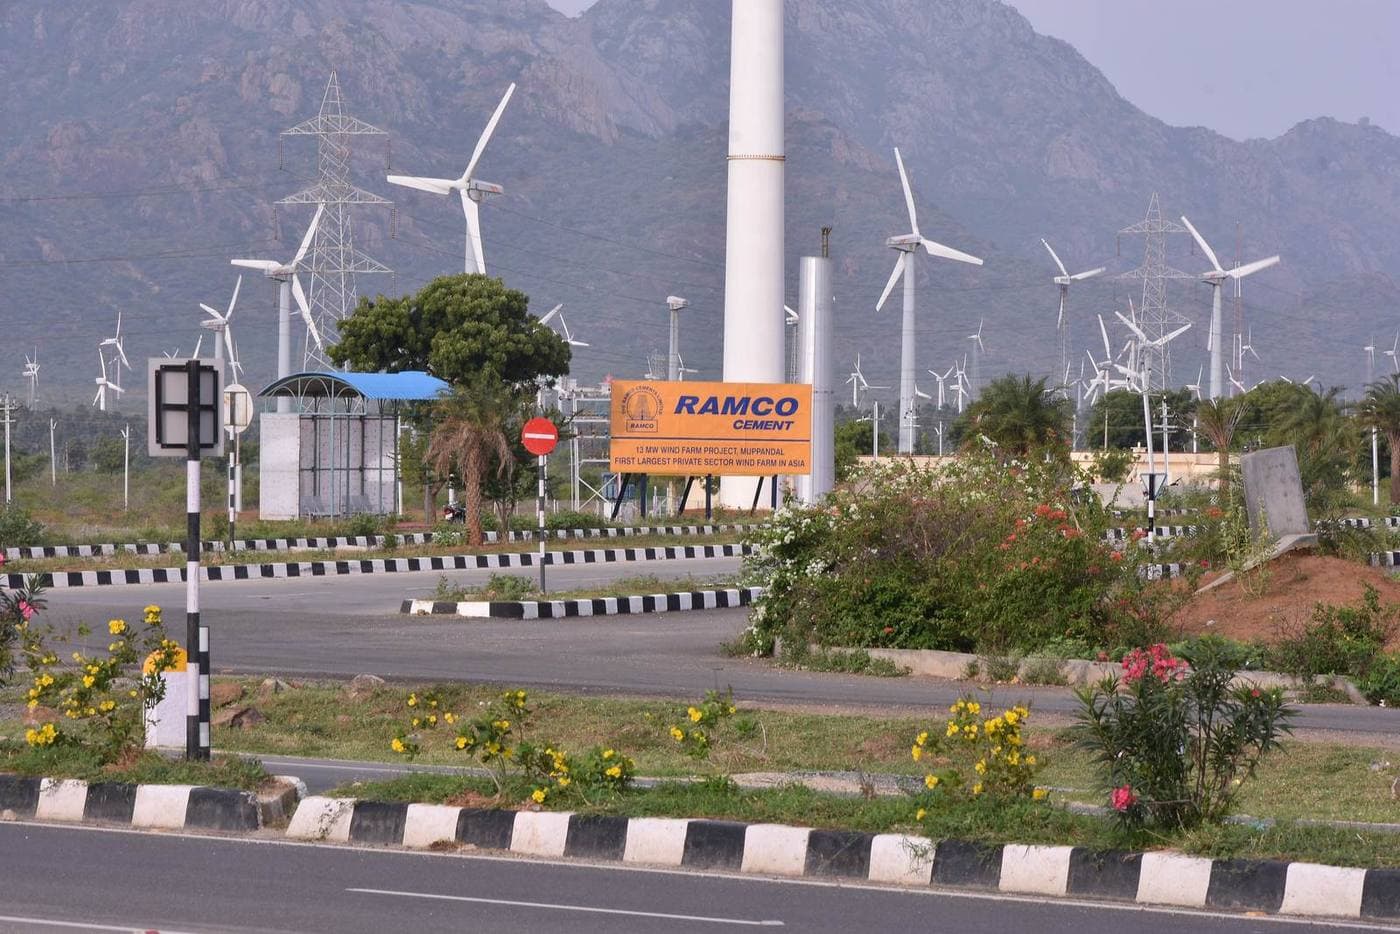
- The FY26 record of 6.05 GW of annual installs would be beaten by 32%; with 59.2 GW already installed and 43 GW under construction, India has a visible 102.2 GW pipeline.
- Turbine manufacturing capacity has doubled to more than 24 GW a year since FY23, and exports hit Rs.12,800 crore — with an ambition to take India’s share of global turbine exports from ~2% to 10% by 2030.
India wind energy capacity is about to enter its steepest growth phase yet. The Indian Wind Turbine Manufacturers Association (IWTMA) told delegates at Windergy India 2026, the industry’s flagship event held from 7 to 9 October, that annual installations will reach 8 GW in FY26-27 and climb to 13.2 GW by FY30-31 — a trajectory that would take cumulative installed wind capacity to roughly 107 GW within five years.
The numbers confirm what Union Minister for New and Renewable Energy Pralhad Joshi told the event: India’s wind sector has set a new record and is preparing to break it. “India’s wind sector has demonstrated strong momentum, with the highest-ever annual installation of 6.05 GW achieved in FY26. We are confident that annual wind installations will surpass this record in FY27, marking another important milestone in India’s wind energy journey,” Joshi said.
Inside the India wind energy capacity roadmap
The projected pathway, published by the Indian Economic Observer’s report on the IWTMA announcement, steps up steadily rather than in one leap:
- FY26-27: 8.0 GW of new installations; cumulative capacity reaches ~62.4 GW
- FY27-28: 9.0 GW; cumulative ~71.4 GW
- FY28-29: 10.0 GW; cumulative ~81.4 GW
- FY29-30: 12.0 GW; cumulative ~93.4 GW
- FY30-31: 13.2 GW; cumulative ~107 GW
That 8 GW figure for the coming year is roughly a third above the India wind installations record of 6.05 GW set in FY26 — a record the minister said gives the government confidence in its national ambition of 100 GW of installed wind capacity by 2030. The base is unusually solid for an emerging-market target: 59.2 GW is already operating and a further 43 GW is under construction, giving India line-of-sight on 102.2 GW of capacity before a single new tender is signed.
The plan leans on grid, not just turbines. The Rs.1.86 lakh crore Green Energy Corridor Phase-III is meant to move renewable power from windy states such as Tamil Nadu, Gujarat and Karnataka to demand centres, underpinning the national goal of 900 GW of non-fossil capacity by 2035. Transmission, more than turbine supply, is now the binding constraint on the pace of build-out.
The manufacturing engine: 24GW a year and a 10% export target
The most consequential number in the announcement may not be a capacity figure at all. India’s annual wind-turbine manufacturing capacity has grown from about 12 GW in FY23 to more than 24 GW today, backed by what IWTMA calls a strong component ecosystem. Exports reached Rs.12,800 crore in FY26 — nearly 50 per cent higher year on year.
Girish Tanti, IWTMA chairman and vice-chairman of the Suzlon Group, framed the export story as a global play: “Our ambition should be to raise India’s share of global wind turbine exports from ~2% today to 10% by 2030, establishing India as a global hub for wind turbines, components, technology and engineering.” As Western developers look to diversify turbine supply away from Chinese manufacturers, a 24 GW-per-year factory base on the subcontinent is a serious alternative — provided the quality story holds.
That is where the technical warning from IWTMA’s chief executive comes in. “As the industry transitions towards higher-rated turbines, we need to accelerate indigenisation across critical components while simultaneously building the manufacturing capacity required to meet growing demand,” CEO Aditya Pyasi said, calling for coordinated effort across manufacturers, component suppliers, technology providers and government. Higher-rated machines — the 3 MW-plus onshore models that make new projects economical on lower-wind sites — still depend on imported critical parts, and that dependence is the weak link in the export ambition.
The event itself underlined the industry’s weight: Windergy India 2026 drew around 400 exhibitors from more than 20 countries and 500 delegates, with dedicated national pavilions from Denmark, Germany and Spain.
Why it matters
India’s announcement deserves attention for what it reveals about where the wind industry is industrialising — not just where turbines spin. The headline growth rate (roughly 32% above a record year) is impressive, but the structural story is the combination of a 102.2 GW visible pipeline, a doubled domestic factory base, and a declared intent to capture a tenth of global turbine exports by 2030. That is not a deployment story; it is an industrial-policy story.
Three implications follow. First, the export target positions India as the principal non-China supplier at exactly the moment European and American developers are being pushed to diversify their supply chains — success would reshape the geography of the global wind market. Second, the Rs.1.86 lakh crore transmission corridor signals that New Delhi understands the real bottleneck: without wires, the turbines are stranded assets. Third, the risk is component depth — Pyasi’s indigenisation warning is the honest footnote to the celebratory numbers, and the 2%-to-10% export-share goal lives or dies on whether India can localise high-rated-turbine components.
India’s wind build-out is also part of a broader offshore push: the country is prototyping offshore wind off Thoothukudi, a signal that its ambitions extend beyond the onshore capacity factors explored in our explainer on capacity factors.